Market overview — definition, scope, and industry significance of High Purity Alumina Market
Our analysis indicates that the High Purity Alumina Market encompasses aluminum oxide with purities exceeding 99.99% (4N to 6N). This sector is foundational for advanced manufacturing, supplying critical precursors like Electronic-Grade Alumina and Battery Separator-Grade Alumina governed by strict regulatory purity thresholds.
Key market drivers, restraints, challenges, and opportunities shaping High Purity Alumina Market
Growth is propelled by surging Li-Ion Batteries demand and LED bulbs adoption. However, energy-intensive production via Hydrochloric Acid or Hydrolysis routes creates logistical bottlenecks. Strategic opportunities lie in scaling green extraction methods developed by innovators like Altech Chemicals Ltd and FYI Resources Limited.
Emerging trends and growth patterns in High Purity Alumina Market
The industry is shifting toward ultra-pure 5N and 6N formulations to support Semiconductor Wafer Substrates and High-Performance Battery Coatings. Regional supply chain localization near major ports in Asia-Pacific and North America is accelerating as firms mitigate cross-border freight disruptions.
COVID-19 impact analysis — how the pandemic affected High Purity Alumina Market and the recovery trajectory
The pandemic caused severe automotive and electronics supply chain contractions, delaying capital-intensive processing plant expansions. Post-crisis, government stimulus in green tech catalyzed a sharp recovery, steering the High Purity Alumina Market industry trends toward localized manufacturing resilience.
Competitive landscape — major players, market concentration, and strategic dynamics
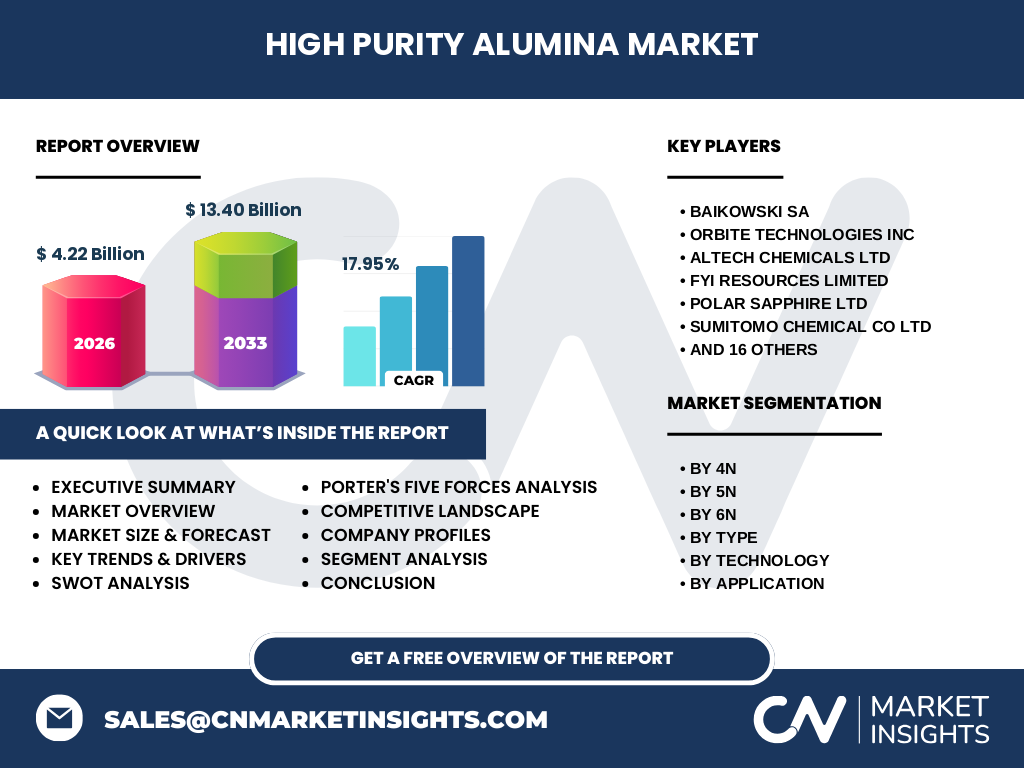
The market features moderate consolidation, led by integrated giants and specialized disruptors. Companies like Baikowski SA, Sumitomo Chemical Co Ltd, and Polar Sapphire Ltd compete through proprietary purification technologies, vertical integration, and strategic long-term supply pacts with tier-one battery cell manufacturers.
Executive summary — high-level synthesis of key findings about High Purity Alumina Market
Valued at 4.22 Billion in 2026, the High Purity Alumina Market is projected to surge to 13.40 Billion by 2033 at a robust CAGR of 17.95%. Electrification and semiconductor expansion are the primary catalysts reshaping this high-barrier sector.
Market forecast — projected growth from 2027 to 2033
Driven by compounding adoption in electric vehicles and photonics, our forecast shows market expansion from 2027 through 2033, culminating at 13.40 Billion. This trajectory reflects an aggressive CAGR of 17.95% underpinned by rising 4N, 5N, and 6N product demand.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans purity grades (4N, 5N, 6N), technologies (Hydrolysis, Hydrochloric Acid), and applications. 4N powers standard LEDs and batteries, while 5N and 6N target High-Brightness LED Sapphire Substrates, Semiconductor Wafer Substrates, and Precision Biomedical & Laboratory Devices.
Regional market analysis — geographic distribution and performance across regions
Asia-Pacific dominates consumption, driven by electronics manufacturing hubs in China, South Korea, and Japan. Meanwhile, North America and Europe emphasize R&D and specialized production of High-Performance Battery Coatings, supported by stringent environmental compliance frameworks mandated by regional authorities.
In-depth regional review — detailed examination of key regional markets
In Asia-Pacific, domestic manufacturing ecosystems accelerate adoption in LED bulbs and Li-Ion Batteries. Conversely, Western markets focus on high-margin Ultra-High-End Semiconductor Applications, partnering with regional innovators like Almatis Inc and American Elements to secure critical mineral inputs.
Company profiles — strategic positioning of leading companies in High Purity Alumina Market
Market participants deploy distinct competitive plays. Orbite Technologies Inc and Altech Chemicals Ltd focus on proprietary green extraction processes, whereas Sasol Limited and Nippon Light Metal Holdings Company Ltd leverage established global distribution networks and massive operational scale.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to bauxite availability, but buyer power is high among major battery cell makers. Threat of substitution is low given strict purity requirements, while high capital expenditure requirements and complex tech keep the threat of new entrants strictly contained.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include exceptional thermal and electrical properties. Weaknesses involve high energy consumption during refining. Opportunities abound in solid-state battery electrolytes, while threats stem from volatile precursor chemical costs and geopolitical trade tariffs affecting raw material flows.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates with bauxite mining or aluminum precursor sourcing, transitioning through complex chemical refining (Hydrolysis/Hydrochloric Acid routes), powder processing, and final component fabrication by end-users in automotive, electronics, and medical device sectors.
Investment insights — strategic recommendations and high-potential areas
Investors should target early-stage ventures pioneering low-carbon extraction and companies scaling Battery Separator-Grade Alumina production. Partnerships with established players like FYI Resources Limited offer high-potential exposure to the expanding 13.40 Billion market.
Conclusion and key takeaways
The High Purity Alumina Market represents a high-growth, technology-driven sector poised to reach 13.40 Billion by 2033. Success relies on navigating environmental regulations, securing stable precursor supply chains, and scaling high-purity 5N and 6N manufacturing capabilities.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary executive interviews across the supply chain, and secondary macroeconomic indicators from industrial associations to ensure absolute analytical precision.
Scope of the report — coverage parameters and limitations
This report covers global market dynamics from 2027 to 2033, analyzing purity grades (4N, 5N, 6N), production technologies, and major end-use sectors. Limitations exclude localized grey-market transactions and unverified pilot-scale production facilities.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry momentum highlights joint ventures focused on low-carbon HPA production. Key firms like Xuancheng Jingrui New Material Co Ltd and Zibo Honghe Chemical Co Ltd have expanded processing capacities to meet surging demand for semiconductor and battery-grade materials.